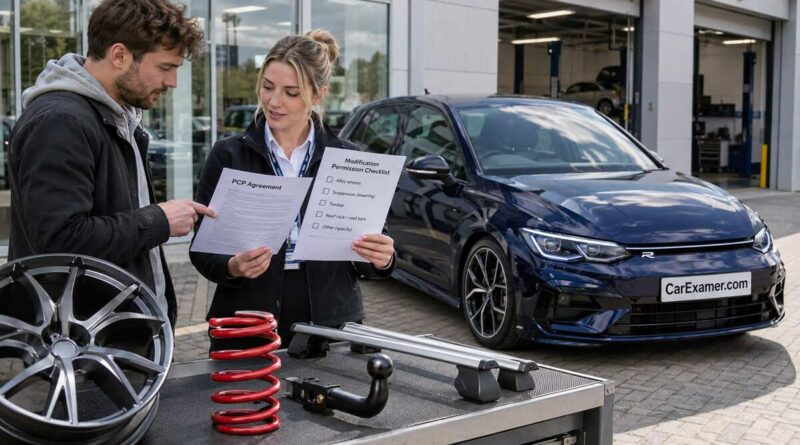
Can You Modify a Car on PCP Finance? UK Guide
Estimated reading time: 8 minutes
Can you modify a car on PCP finance? Sometimes, but you should not assume that you can. A Personal Contract Purchase agreement is a form of finance in which the lender normally remains the legal owner until you make the optional final payment and complete the purchase. The agreement can restrict alterations because the car may be returned and its future value was part of the original calculation.
The safe approach is to read the exact contract and obtain written permission from the finance provider before fitting or changing anything that is not ordinary maintenance. A dealer’s verbal approval may not bind the lender. Even a technically reversible change can affect insurance, warranty coverage, safety, vehicle value or end-of-contract charges.
Who owns a car on PCP?
During a PCP agreement, you are generally the registered keeper and responsible for insurance, tax, servicing and care, while the finance provider owns the vehicle. At the end you normally choose between paying the optional final payment to own it, returning it, or using any available equity in another transaction. MoneyHelper’s PCP guide explains the deposit, monthly payments, mileage allowance, final payment and return choices.
Registration and ownership are different. The V5C is not proof that you can sell or permanently alter the car. Our guide to who owns a financed vehicle explains how PCP, hire purchase, leasing and personal loans differ.
Why PCP agreements restrict modifications
The lender’s risk is linked to the car’s expected value at the end of the term. A modification can change that value, create safety or compliance questions, reduce the market of potential buyers or require work to restore the vehicle. The contract may therefore require the car to remain in its original specification, subject to approved accessories and normal maintenance.
Do not rely on a general internet answer because finance-provider terms differ. Find the clauses dealing with alterations, maintenance, insurance, manufacturer warranty, mileage, condition and return. Ask the lender to confirm its decision in writing and keep that response with the agreement.
What counts as a vehicle modification?
A modification is not limited to engine tuning. Insurers and finance providers may treat any change from the supplied specification as relevant. Examples include:
- ECU remapping, tuning boxes, exhaust, intake or emissions-system changes.
- Lowered or uprated suspension, wheel spacers or non-standard brakes.
- Different wheels or tyre sizes, including changes that affect speedometer accuracy or clearance.
- Towbars, roof systems, body kits, spoilers, wraps, paint or permanent graphics.
- Aftermarket lighting, audio, alarms, trackers, dashcams or wiring changes.
- Interior conversions, seat changes, accessibility equipment or commercial racking.
Ordinary replacement parts can also create a dispute if they do not meet the required specification. Maintenance should follow the contract, manufacturer schedule and applicable warranty requirements. Keep invoices showing what was fitted and by whom.
Are removable accessories allowed?
Floor mats, seat covers, a phone mount or a properly fitted removable roof bar may be lower risk than a permanent alteration, but “removable” does not automatically mean permitted. An accessory can mark trim, damage paint, overload a roof, interfere with airbags or leave missing parts at return.
Check the handbook, load limits and finance terms. Retain all original parts, keys, locking-wheel-nut tools, cables and accessories supplied with the car. Remove approved temporary equipment carefully and repair any resulting damage to the required standard before return.
Get written permission before work starts
Describe the proposed change precisely. Include the part, manufacturer, installer, effect on wiring or bodywork, whether it can be reversed and whether original parts will be retained. Ask the finance provider:
- Is the modification permitted under this agreement?
- Must an approved installer or part be used?
- Must the car be restored before return?
- Will written evidence or an inspection be required?
- Could the change affect the guaranteed future value or return charges?
Permission from the lender is only one part of the decision. You may also need approval from the insurer, and the vehicle manufacturer may take a different position on warranty coverage.
Tell the insurer before modifying the car
Ask the insurer whether the proposed change must be declared before fitting it. A modification can change the premium, terms or willingness to cover the car. Do not wait for renewal or a claim. Keep the insurer’s written response and make sure the policy description is accurate.
Some changes can affect vehicle construction and use requirements. Lighting, emissions equipment, number plates, window tint, wheel fitment and towing equipment must remain lawful and safe. Finance-company permission does not make a non-compliant alteration legal.
Manufacturer and extended warranty risks
A modification does not automatically cancel every warranty claim, but a provider may refuse a claim where the change caused, contributed to or complicated the fault, subject to the warranty terms and applicable rights. An engine remap, altered wiring or non-standard suspension can create obvious areas of dispute.
Read the manufacturer warranty and any extended used-car warranty. Ask for a written position before work. Do not remove diagnostic evidence or return the software to standard in an attempt to hide a previous change. Accurate disclosure is safer than creating a later disagreement about what was fitted.
Modifications and your consumer rights
Statutory rights and warranty terms are not identical. If a car supplied by a trader was not of satisfactory quality, fit for purpose or as described, a later modification does not automatically erase every right. However, it can make causation and evidence more complicated. The seller or finance provider may argue that the alteration caused the symptom or prevented proper diagnosis.
If a fault appears, record it and contact the supplying dealer and finance provider before altering, dismantling or remapping the vehicle. Give them a reasonable opportunity to assess it where required. Preserve diagnostic reports, photographs and invoices.
What happens when the PCP car is returned?
A returned car is normally checked for mileage, condition, missing items and compliance with the agreement. MoneyHelper notes that damage or excess mileage can lead to charges. The BVRLA fair wear and tear standard distinguishes normal deterioration from damage and is widely used for leased and financed vehicles.
Inspect the car well before collection. Check wheels, tyres, glass, paint, trim, lights, accessories, warning lights, service evidence, keys and charging cables where relevant. A pre-return vehicle inspection can document accessible condition, but the finance provider applies its own contractual return standard.
If a modification was authorised, keep the permission and invoices ready. If the lender required reversal, use a competent repairer and retain evidence. Poorly restored wiring holes, paint edges or damaged fixings may still fall outside acceptable condition.
Can you modify the car after paying the final payment?
After the optional final payment and any completion requirements are satisfied, ownership normally transfers to you. Confirm that the agreement is fully completed before treating the car as yours. You must still notify the insurer, keep the vehicle roadworthy and consider manufacturer or extended-warranty terms.
If modification is a central part of your plan, compare PCP with cash or a personal loan, where you normally own the vehicle from purchase. Our guide to types of car finance explains how ownership and total cost differ.
Voluntary termination and early settlement
Do not assume that modifying the car, returning it early or paying a settlement figure are interchangeable routes. MoneyHelper’s early car-finance guidance explains voluntary termination and settlement. PCP’s 50% voluntary-termination threshold includes the final payment, so it may be reached late in the term.
The Financial Ombudsman considers the agreement, condition evidence and proportionality when reviewing disputes about car-finance damage charges. If you dispute a charge, request the inspection report and photographs, compare each item with the agreement and return standard, and complain to the finance provider in writing before escalating through the available process.
Practical rule before changing a PCP car
Assume the modification is not permitted until the finance provider confirms otherwise in writing. Then check insurance, warranty, legal compliance, installation quality and the return requirement. If approval is refused, either leave the car standard or consider whether completing the purchase legitimately fits your finances. Never conceal a change or rely on the hope that it will not be noticed.
PCP modification questions
Can I fit a dashcam to a PCP car? Ask the finance provider and insurer. A removable plug-in unit may be acceptable, while hard-wiring, drilled trim or damaged headlining can create warranty or return concerns.
Can I wrap a PCP car? Only with written permission. A wrap can affect paint, hide damage and require professional removal. Confirm who pays for removal and what condition is required at return.
Can I change the alloy wheels? Do not assume so. Wheel size, load rating, offset, tyre specification and insurance matter. Retain the originals and follow the lender’s written conditions.
Can I remap a PCP car and return it to standard later? A remap can affect reliability, emissions, insurance, warranty and vehicle records. Reversing the software later does not remove those risks or make an unauthorised change acceptable.